Two questions, not one
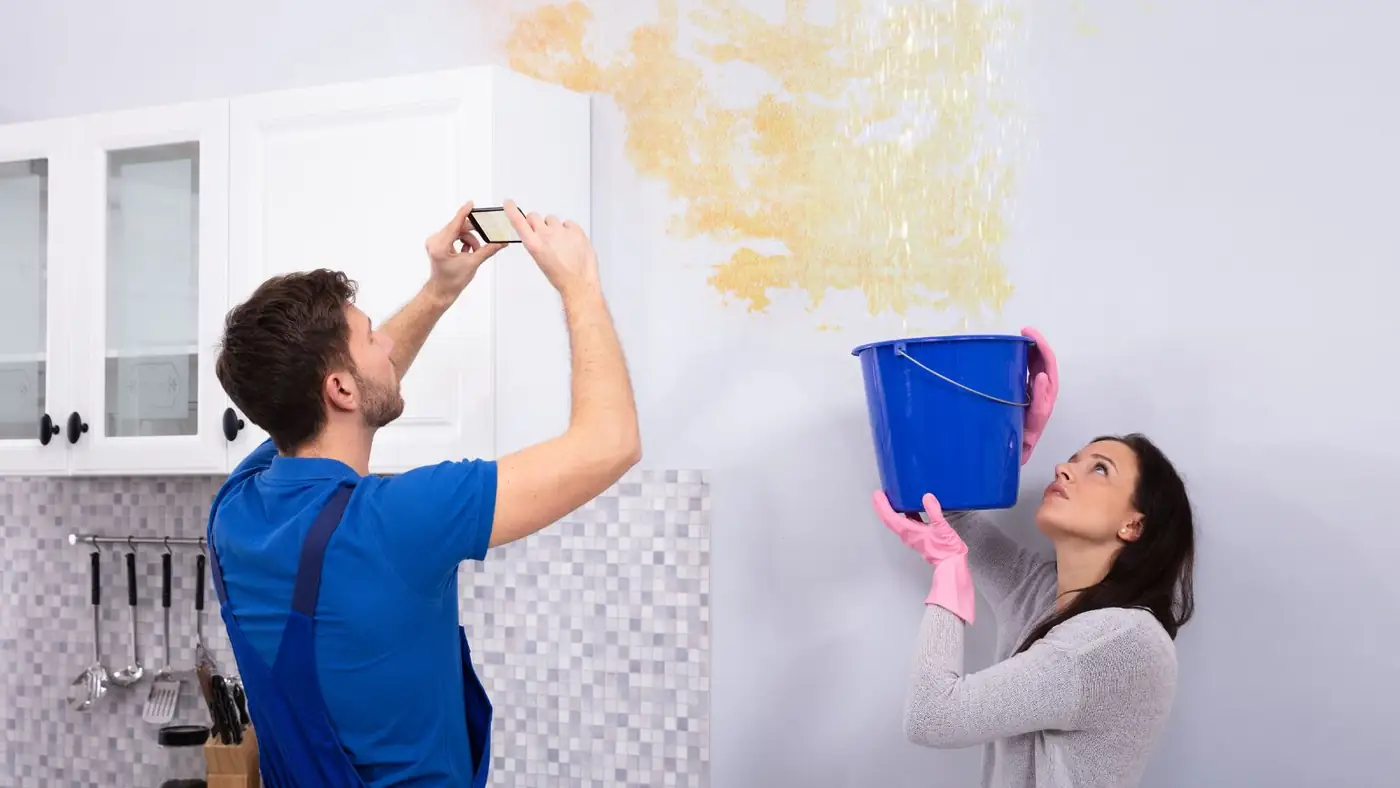
After a leak, the real question is two questions. Is this the kind of loss my policy is meant to cover? And is the damage big enough to be worth a claim? A claim means filing a request with your insurer to pay for covered damage beyond your deductible. A repair-only route means you pay and do not file.
Nobody can answer this for you without reading your policy. We can tell you what the damage is. Your insurer or agent can tell you what the policy says. We do not give legal advice, and this page is general information only.
A quick map of common situations
| Situation | Usually looks like | What to ask your insurer |
|---|---|---|
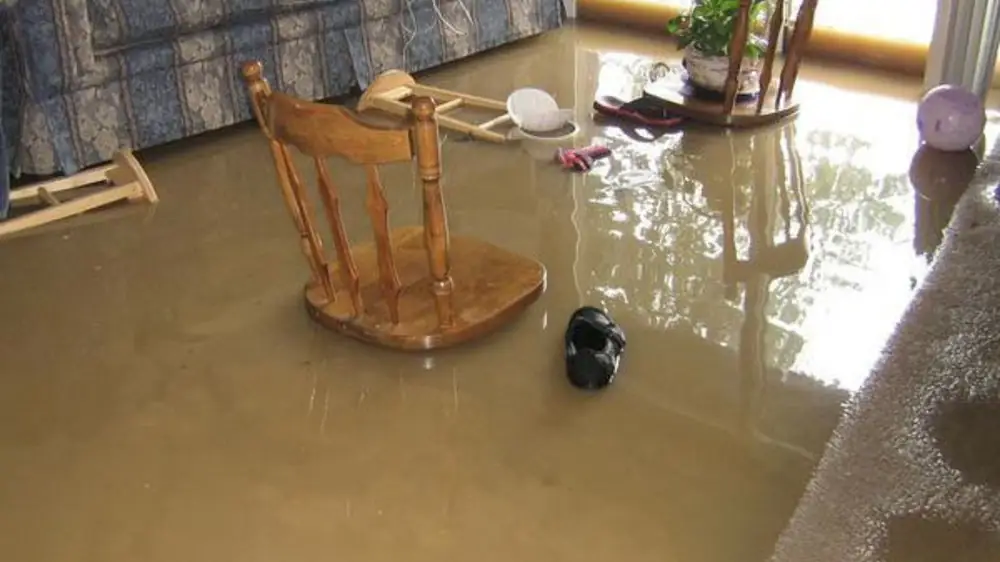
| Supply line burst, several rooms wet. | A claim question, since the damage is sudden and spread out. | Is this sudden and accidental, what is my deductible and what does mitigation include? |
| Small drip under a sink, one cabinet. | Often a repair-only question if the cost is below the deductible. | How do claims affect my record, and is there a reporting requirement? |
| Stain from a slow roof or pipe leak. | Uncertain, because gradual damage is often excluded. | How does my policy treat leaks over time? |
| Water entered from outside after heavy rain. | A flood question, usually excluded from standard policies. | Do I have flood coverage, and when did it start? |
| Sewer or drain backup. | Depends on endorsements on the policy. | Do I have water backup coverage, and what are its limits? |
| Renter with damaged belongings. | A renters policy question for contents. | What does my renters policy cover, and what should the landlord handle? |
A lower-cost damage can still be worth reporting if the cause is unclear. Ask before you decide.
Deductible versus the size of the damage
Your deductible is what you pay before coverage applies. If the damage will clearly cost less than that, a claim may bring nothing back. If it is close, or you cannot yet see how far the water went, wait for readings before deciding.
Size is hard to judge by eye. Water moves into wall cavities, under flooring and above ceilings. A small stain can be the edge of a large wet area. That is why moisture readings come before any decision.
Sudden and accidental versus gradual
Sudden and accidental damage, like a burst supply line or a failed water heater, is often covered. Gradual leaks and neglect, like a slow drip behind a toilet, are often not. The line between them is where many claims turn.
That is why the source matters. A plumber's note on what failed and when helps. So do dated photos that show how the damage looked on day one. Check your policy and ask your insurer how it defines each case.
Mitigation costs versus rebuild costs
Water damage work often has two parts. Mitigation is the emergency side: extraction, drying, equipment and removing materials that cannot be saved. Rebuild is putting the house back: drywall, flooring, trim and paint.
They are priced and scheduled differently. Mitigation is time-sensitive, because it limits further damage. Rebuild can wait for decisions about the claim. Our water damage repair work covers the second part, and we explain scope and price before work starts.
Want the damage measured first?
Call (818) 337-2642. We document and explain before you decide.
Flood cover, contractors and permits in Studio City
The California Department of Insurance says homeowners and commercial policies typically exclude flood, mudslide and debris flow. Flood cover comes through the National Flood Insurance Program, sold by licensed agents. A new NFIP policy generally takes effect 30 days after purchase.
So if you do not carry flood cover today, buying it after a storm is on the horizon will not help that storm. Ask your agent what you carry before you need to know.
For the repair side, the California Contractors State License Board lets you look up a contractor's license online. Do that before you sign anything. For permits, ask the correct city building office. In the City of Los Angeles that is LADBS, while Burbank is a separate city with its own water and power utility and its own permit office.
What happens if you wait
Waiting costs money in a specific way. The EPA says to dry wet areas within 24 to 48 hours to prevent mold growth. Past that, drywall softens, hardwood cups and mold becomes a possibility, which adds to the work.
Most policies also expect you to protect the property from further damage. Emergency drying is often that protection. You do not have to decide about the claim to start it. Keep receipts and photos, and tell your insurer promptly. For a home in Burbank, where more than 62 percent of the housing was built before 1970, older supply lines and drains are a common reason to act quickly.
Renters, owners and HOA
- Renters: report the leak to the landlord in writing right away. Your renters policy typically deals with your belongings, and the building's policy deals with the structure.
- Owners: your homeowners policy deals with the house and, depending on the policy, your belongings. You choose how to proceed.
- HOA members: the association's master policy and your own policy may each cover different parts of the unit. Ask the HOA manager which walls and fixtures the association handles.
In Encino, where about 61.6 percent of housing was owner-occupied in the 2000 census era source, many leaks are an owner's decision. Condos and townhomes are the exception, since the HOA may be involved.
How a claim can affect renewals
Ask your agent how claims are rated, rules vary. Beyond that, we cannot say how any one claim would be treated.
Document first, decide later
Stop the source
Shut off the water to the broken line or appliance if you can do so safely.
Photograph everything
Take wide and close photos and a video before anything is moved.
Start drying and keep receipts
Emergency drying limits damage while you gather facts.
Call your agent
Ask the questions in the table above and decide with the scope in hand.
General information only
This page is not legal advice and does not predict any claim result. For questions about your policy rights, talk to your insurer, your agent or a qualified professional.
Should I file if the damage is only a little over my deductible?
It is your call. Ask your agent how claims are rated and whether the repair cost is likely to exceed the deductible by enough to matter.
Can I start drying before I contact my insurer?
Yes, in most cases, and many policies expect it. Photograph first, keep receipts, and then notify your insurer promptly.
If a water main breaks on my street, is that a claim?
That depends on the cause and where the water entered your home. LADWP handles main repairs. Ask your insurer how it treats water from outside.
How do I check a contractor before hiring?
Look up the license on the California Contractors State License Board website. Ask what the scope covers, and whether the crews follow ANSI/IICRC S500.
Do I need a permit for the repair?
It depends on the work. Ask the city building department that covers your address. In Los Angeles that is LADBS. In Burbank it is the City of Burbank.